


An oil and gas severance tax is a state charge on extracting oil or gas, measured either by value or by volume. Rates vary widely by state and well type, and the effective rate an owner actually pays is often far below the headline number because of exemptions and credits. Read the statutory rate as a starting point, never the final answer.
TL;DR:
- Colorado’s statutory rates of 2% to 5% averaged about 1.6% effectively from 2013 through 2022 after credits and exemptions, so model net liability.
- Louisiana charges 6.5% on oil from wells completed on or after July 1, 2025, while older wells remain at 12.5%; verify completion dates.
- Stripper wells producing roughly 10 to 15 barrels daily or less may qualify for reduced rates or exemptions, depending on state rules.
- Operators remit the tax, but it usually reduces royalty and working interest payments; check statements and record the charge as a production expense.
- Value based taxes rise and fall with sale prices, while volumetric taxes charge per barrel or thousand cubic feet; confirm current state rules before forecasting.
Table of Contents
- How do severance tax rates compare across states?
- Why does the effective rate differ from the statutory rate?
- Which exemptions and incentives change a well’s tax?
- Who pays the tax and how does it affect your returns?
- What changed in 2024 through 2026?
- Where can you verify these numbers and run your own estimate?
- What should you check first when judging severance tax exposure?
- Looking for tax-advantaged energy deals beyond the research?
- FAQ
- Sources
How do severance tax rates compare across states?
States build this tax in two ways. Value-based states charge a percentage of what the product sells for. Volumetric states charge a fixed amount per barrel or per thousand cubic feet. Some mix both, and a few add a separate extraction tax on top.
- Value-based: Texas, Louisiana, Michigan and North Dakota (oil) tie the tax to sale value, so it rises and falls with price.
- Volumetric or sliding scale: North Dakota gas uses a per-mcf rate, and Utah uses price bands, such as 3% up to $13 per barrel and 5% above.
- Unusual designs: New Mexico taxes value at the time and place of severance, and Montana sets rates by production category and vintage. Tax structures vary by state, so check each state’s current rules.
Rates change, so confirm any figure on the state revenue site before you model it. Check Wyoming and Oklahoma’s state-specific schedules and well-type rules before modeling a project.
Why does the effective rate differ from the statutory rate?
The statutory rate is what the law names. The effective rate is what operators and owners actually pay once credits and exemptions apply. The rough math: gross income × statutory rate − credits and exemptions = net liability.
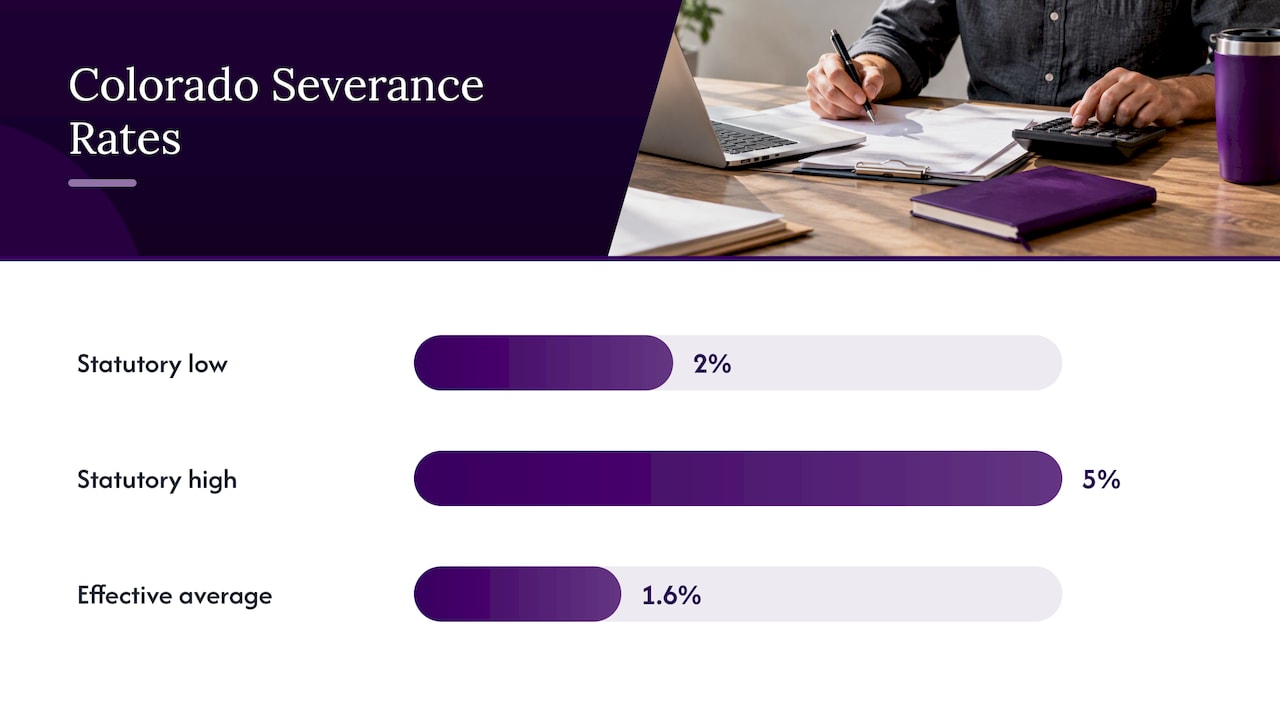
Colorado shows the gap clearly. Its graduated statutory rates run 2–5%, yet a legislative memo finds that ad valorem credits and exemptions pull the effective rate to an average near 1.6% for 2013–2022.
- Ad valorem credits: Local property taxes paid on production can be credited against the state severance bill.
- High-cost gas designations: Texas reduces the gas rate for qualifying high-cost wells.
- Stripper and new-well incentives: These lower the burden further, as the Texas Railroad Commission describes.
Colorado’s effective severance rate averaged about 1.6% across 2013–2022, well below its 2–5% statutory range. A project priced on the headline rate would look materially worse than it really is.
Which exemptions and incentives change a well’s tax?
Four levers do most of the work, and each depends on dates or production thresholds you need to verify.
- Stripper well exemptions: Low-volume wells, commonly those producing roughly 10–15 barrels per day or less, often get reduced rates or full exemptions. North Dakota says stripper wells may be exempt, and Utah exempts them too.
- New-well and completion-date rules: Louisiana taxes oil from wells completed on or after July 1, 2025, at 6.5%, while older wells stay at 12.5%. The completion date decides the rate.
- Restimulation and workover exemptions: Texas added a short-term restimulation exemption in 2025 under HB3159.
- High-cost gas reductions: Texas lowers the gas rate for wells that cost more to drill and complete.
Louisiana also lists reduced rates for incapacity, inactive, orphaned and reclaimed oil, so one state can carry several rates at once.
Who pays the tax and how does it affect your returns?
The operator remits the tax to the state, then typically deducts it from royalty and working-interest payments. You see it on your check detail, which means owners bear the economic cost even though they never file the state return.
- Find the severance line on each royalty or revenue statement.
- Check how often your state requires filing. Frequency varies with the amount owed, and Utah requires electronic filing, for example.
- Treat the tax as a production expense, since severance taxes are generally deductible as a cost of doing business.
- Run the after-tax math with a CPA.
Your actual result depends on your entity type and circumstances.
Severance-tax collections are volatile: EIA documented sharp drops in top producing states when oil prices fell in 2014–2015. Falling prices shrink a value-based tax, which helps owners per barrel but signals weaker revenue overall.
What changed in 2024 through 2026?
Three developments matter most for valuing assets today.
- Louisiana Act 295 (2025): The oil rate dropped to 6.5% for wells completed on or after July 1, 2025, while legacy wells remain at 12.5%. Timing rules like this reward careful date tracking.
- Texas 2025 restimulation exemption: HB3159 added a short-term exemption alongside the ongoing high-cost gas reduced-rate mechanics.
- Colorado credit changes: Ad valorem credit shifts and effective-rate memos show that net collections can fall dramatically in some years.
States also depend heavily on these receipts, which is why the Tax Policy Center notes revenue can drop sharply within a single quarter when prices fall.
Where can you verify these numbers and run your own estimate?
We connect accredited investors with vetted U.S. energy operators offering tax-advantaged projects. To estimate tax effects yourself, use our free Oil & Gas Tax Deduction Calculator.
- Read our oil and gas tax advantages for high earners guide for deal-structure background.
- Use our 2026 tax filing guide once you know your exposure.
- Pair this article with our depreciation methods guide and depletion primer, since both interact with severance costs.
- Confirm every rate on the state revenue or tax commission page, and consult a qualified CPA before you plan around it.
If financing is part of your plan, this partner article on HELOC interest deductibility covers one borrowing structure.
What should you check first when judging severance tax exposure?
Start with the effective rate, not the headline. Then verify the completion date, the stripper-well test and local ad valorem levies, because each can flip the answer. Finally, stress-test cash flow against volatility. This can help reveal potential surprises.
— Sharif
Looking for tax-advantaged energy deals beyond the research?
Understanding severance tax is half the job. The other half is finding projects where the tax picture is already worked out. Fieldvest is a marketplace where accredited investors can explore producing assets, development projects and energy infrastructure.
- Run your numbers in our free tax deduction calculator.
- Learn how to lower your taxes with oil and gas investments.
If you are accredited, review our investment materials and talk with your tax advisor about fit.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What is the severance tax rate for natural gas in Texas?
Texas imposes a baseline gas rate of 7.5% as of 2026, according to the Railroad Commission. High-cost gas reductions and other incentives can lower what a specific well actually pays.
What tax breaks do oil companies get on severance taxes?
States offer stripper well exemptions, new-well incentives, restimulation exemptions and high-cost gas reductions. Credits for local property taxes, as in Colorado, can cut the effective rate well below the statutory one.
Are severance taxes deductible on federal returns?
Generally yes. Severance taxes are treated as a cost of doing business and deducted as a production expense, which lowers federal taxable income. Confirm your specific treatment with a CPA.
Is the federal tax rate on severance pay the same as this tax?
No. Severance pay is a payment to an employee leaving a job and is unrelated to an oil and gas severance tax, which is a state charge on extracting oil or gas. The two share only a name.
Recommended

Get the Fieldvest Energy Brief
and AI-driven demand shifts — curated for accredited investors. Smart. Strategic. Tax-advantaged.



