
Yes, a Self-Directed IRA can hold oil, gas, and royalty interests, but only under specific conditions. The asset must be titled correctly in the IRA’s name (or an IRA-owned LLC), the income type matters because working interests can trigger unrelated business taxable income (UBTI) while royalties usually don’t, and the position needs to be sized with illiquidity in mind. Get the asset classification wrong or route income through a personal account, and you risk disqualifying the entire IRA. The section below breaks down which asset types fit and why.
TL;DR:
- Royalty interests are preferable for SDIRA oil investments because they are passive and less likely to trigger unrelated business taxable income.
- Proper legal titling and document accuracy are critical; errors can lead to disqualification or incorrect income routing into personal accounts.
- UBTI from working interests can significantly increase tax liability, especially if the IRA borrows funds or is structured as a partnership that issues K-1 forms.
- Due diligence on operators, reserve estimates, and fee transparency is essential to avoid overpaying or investing in high-risk deals.
- Maintaining strict compliance and conservative position sizing ensures the IRA remains tax-advantaged and reduces IRS-related risks.
Table of Contents
- Self Directed IRA Oil and Gas Ownership: How Mineral, Royalty, and Working Interests Work
- Tax and Compliance Mechanics: UBTI, Debt-Financed Property, and Form 990-T
- Custody, Titling, and Structure Choices for an SDIRA Oil Investment
- Due Diligence Before You Commit IRA Capital to an Oil Deal
- Step-by-Step Checklist to Execute a Compliant SDIRA Oil or Royalty Purchase
- Where Fieldvest Fits Into an SDIRA Oil Strategy
- What Actually Separates a Smart SDIRA Oil Investor From a Reckless One
- Ready to evaluate vetted oil or gas deals for your SDIRA?
- Sources
- FAQ
Self Directed IRA Oil and Gas Ownership: How Mineral, Royalty, and Working Interests Work
Oil and gas interests come in several legal flavors, and the flavor you pick determines how well it fits inside a retirement account. Fee minerals are outright ownership of the oil and gas beneath a tract of land. A royalty interest entitles the holder to a percentage of production revenue without paying for drilling or operating costs. An overriding royalty interest (ORRI) works similarly but is carved out of a lease rather than tied to the mineral estate itself. A net profits interest (NPRI) shares in profits after costs. A working interest means you own a share of the operation itself, including the obligation to pay your portion of drilling and operating expenses.
For self directed IRA oil and gas investing, royalty-style interests are usually the cleanest fit because they’re passive by design. You collect a check; you don’t manage a rig. Working interests, by contrast, can pull the IRA into active trade or business activity, which is exactly what triggers UBTI exposure.
Every document tied to the deal needs to carry the IRA’s exact legal name, not yours personally. That includes:
- The mineral or royalty deed
- The division order the operator uses to route payments
- Subscription paperwork if the interest is offered through a fund or syndication
- Any assignment or transfer agreement
Get a division order wrong, and checks can land in your personal mailbox instead of your custodian’s account, which is its own compliance headache.
Tax and Compliance Mechanics: UBTI, Debt-Financed Property, and Form 990-T
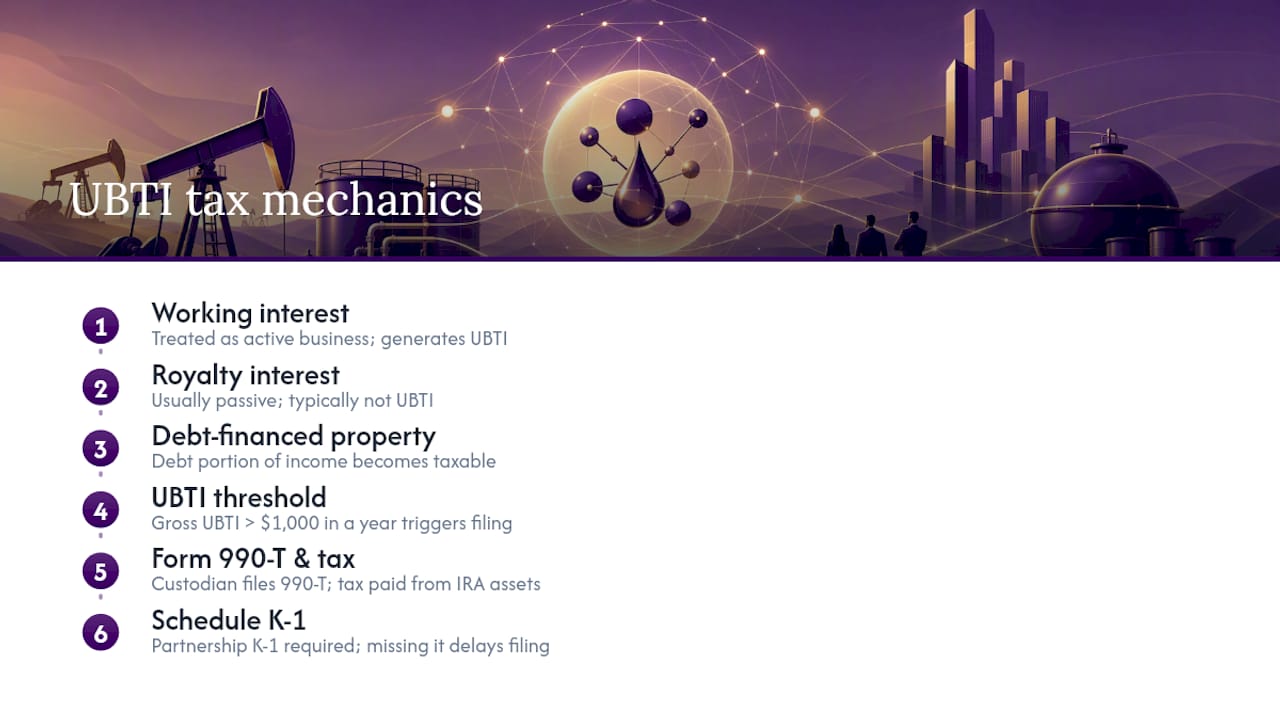
This is where most SDIRA oil and gas mistakes actually happen, and it’s a tax mechanics problem more than an investment problem. IRAs are generally tax-exempt vehicles, but the IRS carves out an exception for unrelated business taxable income. When an IRA earns more than $1,000 in gross UBTI in a year, the account owner (through the custodian) must file IRS Form 990-T, and the tax owed is paid out of IRA assets, not your personal checking account.
Working interests typically generate UBTI because the IRA is treated as participating in an active trade or business, not simply collecting passive income. Royalty interests usually don’t, since IRS guidance treats royalty income as passive under the same logic that exempts rents and dividends in most cases.
UBTI can get expensive fast. Because IRAs and trusts are taxed on a compressed schedule, UBTI can climb into the highest bracket at a much lower income threshold than an individual return would, which is why even a modest working interest position can produce a disproportionate tax bill.
Two other wrinkles deserve attention. First, debt-financed property rules mean that if the IRA borrows to acquire an interest (leverage inside a working interest deal, for example), the debt-financed portion of income becomes taxable regardless of asset type. Second, working interests are frequently structured as partnerships, which means the IRA receives a Schedule K-1 each year that your custodian needs in order to calculate UBTI correctly. Miss that K-1 or hand it in late, and the 990-T filing timeline slips with it.
Custody, Titling, and Structure Choices for an SDIRA Oil Investment
Your custodian administers the account. It does not evaluate whether the oil deal is any good. Opening a Self-Directed IRA is typically a fast administrative process, often around 15 minutes, but that speed is precisely why the real diligence burden falls on you and your advisors.
The purchase workflow generally runs like this:
- Fund the SDIRA through a rollover, transfer, or new contribution.
- Submit a Direction of Investment form (often bundled into a “Purchase Kit”) instructing the custodian to acquire the specific interest.
- Confirm every document lists the IRA, or the IRA-owned LLC, as the legal owner, not you personally.
- Route all income and expenses exclusively through the custodian or the LLC’s dedicated bank account.
Some investors set up an IRA-owned LLC, sometimes called checkbook control, to execute purchases faster without routing every transaction through the custodian. That speed comes at a cost: checkbook control structures raise the administrative bar and the compliance risk, particularly around commingling personal and IRA funds, which is one of the most common ways investors accidentally trigger a prohibited transaction.
Pro Tip: Never let a royalty check get deposited into your personal account “just this once” to expedite something. That single deposit can be treated as a distribution, and it can jeopardize the account’s tax-exempt status.
Due Diligence Before You Commit IRA Capital to an Oil Deal
Tax compliance protects your IRA’s structure. Due diligence protects your capital. Both matter, and skipping either one defeats the purpose of the strategy.
Before wiring IRA funds into any oil, gas, or mineral deal, verify:
- Title and division order accuracy — confirm the seller actually owns what they’re selling and that payment routing matches the IRA’s legal name.
- Independent reserve or engineering review — don’t rely solely on the operator’s own production estimates.
- Operator track record — how have their prior wells or royalty pools actually performed against projections?
- Decline curve assumptions — overly optimistic production decline assumptions are one of the fastest ways deals get overpriced; a closer look at how projected returns are calculated helps spot inflated projections before you commit.
- Fee transparency — opaque management or sponsor fees erode returns quietly over years.
- Related-party structuring — a deal where the sponsor, seller, and manager are all connected entities deserves extra scrutiny for prohibited transaction risk.
Oil and gas royalty income is also inherently lumpy. Commodity prices swing, wells decline, and there’s no public market to exit a mineral interest overnight. Size positions as long-term, illiquid allocations, not as a piece you might need to liquidate in eighteen months.
Step-by-Step Checklist to Execute a Compliant SDIRA Oil or Royalty Purchase
Running through the mechanics in order keeps the paperwork clean and the IRS off your back.
- Fund the account. Complete a transfer or rollover into a Self-Directed IRA before shopping for deals.
- Select a custodian experienced with oil and gas or mineral-rights transactions specifically, not just real estate.
- Vet the deal independently using title review, reserve reports, and operator history, separate from anything the custodian tells you.
- Submit the Direction of Investment and confirm the resulting deed, division order, and any operating agreement all name the IRA or IRA-owned LLC correctly.
- Track gross unrelated business income annually, and flag the account for Form 990-T review the moment it looks like it will cross $1,000.
- Assemble your advisor team early: a tax professional familiar with UBTI, an oil-title attorney, an independent engineer for reserve verification, and a direct line to your custodian’s alternative-asset team.
Pro Tip: Print your document checklist before you sign anything. Every deed, division order, and subscription agreement must reflect identical IRA titling language, and inconsistency across documents is one of the most common reasons custodians reject or delay a purchase.
Reviewing a checklist for handling oil investment paperwork before you engage a custodian saves a round trip when documents come back with the wrong entity name.
Where Fieldvest Fits Into an SDIRA Oil Strategy
Some platforms connect accredited investors with vetted U.S. energy operators, which matters most at the step most SDIRA guides skip: finding a deal worth putting IRA capital into in the first place. Beyond deal access, some providers offer resources on structuring tax-advantaged oil and gas positions and evaluating projects for realistic return assumptions. None of that replaces independent tax counsel or a title review specific to your deal…
What Actually Separates a Smart SDIRA Oil Investor From a Reckless One
The investors who do this well aren’t chasing the biggest deduction or the flashiest decline curve. They’re the ones who vet the operator first and worry about tax structuring second, because a bad well with great tax attributes is still a bad well. Keep positions conservative relative to total retirement assets, run a UBTI check every single year rather than assuming last year’s structure still applies, and paper every transaction as though an IRS examiner will read it eventually. That discipline, more than any single tax strategy, is what keeps an SDIRA oil position from becoming a liability.
— Sharif
Ready to evaluate vetted oil or gas deals for your SDIRA?
Some platforms offer accredited investors access to vetted U.S. oil and gas projects instead of cold-sourcing operators and hoping the title work holds up. These platforms often pair deal access with tax-focused resources tailored for high-income investors weighing direct energy exposure against the deduction and compliance questions this article just walked through.
Start by running a deal through the free oil and gas tax deduction calculator to see what a first-year deduction could realistically look like, then review current vetted opportunities on Fieldvest. Access is limited to accredited investors, and speaking with an advisor before committing IRA capital is always the right first move.
Sources
Confirm UBTI and filing mechanics directly with IRS Publication 598 and review custodian-specific guidance through The Entrust Group before finalizing any purchase.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
- Publication 598 (Tax on Unrelated Business Income of Exempt Organizations) — IRS
- Drilling for Returns, Dodging Landmines: SDIRA Oil & Gas 101 — uDirect IRA Services
FAQ
What are the top self-directed IRA companies for oil and gas?
Look for custodians with specific experience administering mineral, royalty, and working interest assets rather than generalist real estate custodians, since document requirements and UBTI tracking differ meaningfully for energy assets.
What is the best U.S. oil stock to buy for retirement income?
There’s no single “best” pick; direct oil stocks trade differently from direct royalty or mineral interests held in an SDIRA, and stock exposure doesn’t carry the same UBTI or titling considerations as a direct working interest.
How many people have $1,000,000 in their retirement account?
Seven-figure retirement balances remain relatively rare nationally, which is one reason high-income investors increasingly look at alternative assets like direct oil and gas royalties to accelerate tax-advantaged growth beyond typical stock and bond allocations.
Is a self-directed IRA a good investment for oil and gas exposure?
It can be, for accredited investors who correctly title the asset, favor passive royalty interests over working interests to limit UBTI exposure, and treat the position as a long-term, illiquid allocation rather than a short-term trade.
Recommended

Get the Fieldvest Energy Brief
and AI-driven demand shifts — curated for accredited investors. Smart. Strategic. Tax-advantaged.