

If you have just received proceeds from a company sale, an IPO, a secondary or a large equity exercise, the work now is to size the tax bill, set cash aside, and decide whether a U.S. oil and gas investment belongs in the plan. An eligible direct investment in U.S. oil and gas can produce intangible drilling cost (IDC) deductions, depreciation and depletion. The result depends on structure, your role, the costs incurred and the limits that apply to you. Below is the sequence we walk through with high earners, with the IRS and statutory sources behind each step.
TL;DR
- Reserve cash for taxes first. The IRS may expect an estimated payment for the quarter in which a large gain is realized, not at year end.
- Oil and gas deductions come from three pieces: IDC (generally expensed under §263©), tangible equipment (depreciated) and depletion (as production occurs).
- Deductions are not automatic. Structure, your role, basis, at-risk and passive-activity rules decide what you can actually claim.
- Deductions taken now can come back as ordinary income on a sale under §1254, so plan the exit before you enter.
- Bring your CPA in before you commit capital, not after you file.
Table of Contents
- What can still be planned after the money arrives
- Step 1: Size the bill and set a tax reserve
- Step 2: Plan estimated payments around the gain
- Step 3: Understand where oil and gas fits
- A side-by-side view of the three deduction types
- What limits the deduction
- Before you claim anything: a documentation checklist
- Think about the exit on day one
- A worked way to frame the decision
- Our perspective
- Where Fieldvest fits
- FAQ
- Sources
What can still be planned after the money arrives
Much of the best tax planning for an exit happens before closing: valuation, deal structure, entity structure, estate and charitable planning. Advisory guidance on pre-liquidity planning lists these as the items to settle early. One chief tax strategist quoted by InvestmentNews described transaction planning as architectural, meaning ownership, trusts, charitable intent, residency and post-sale deployment are shaped over time rather than at closing.
That does not mean the window has shut once the wire lands. After proceeds arrive you can still:
- Project your federal and state tax for the year and fund a reserve.
- Adjust estimated payments so you avoid underpayment penalties.
- Revisit estate and investment strategy with the new balance sheet in view.
- Choose how to redeploy part of the proceeds into assets that carry their own tax treatment, such as real assets with depreciation and depletion.
If your deal is still open, treat this article as a map of what to ask your advisors now. If it has closed, start with the cash.
Step 1: Size the bill and set a tax reserve
Before you spend or reinvest anything, work out what you owe. A practical checklist, echoed in a 2026 equity-event tax checklist, is to identify each taxable transaction, project household federal and state tax, reserve the cash, and reconcile grant, exercise, withholding, broker and basis records.
A few points that trip up founders, executives and crypto holders alike:
- Withholding rarely matches the real bill. Supplemental withholding on equity compensation can land well below your marginal rate.
- Basis records matter. A missing basis figure turns into a larger gain on paper.
- State tax can be large. Your state of residence and any states where the business operated may each want a share.
- Keep the reserve in cash or short-term Treasuries, not in the investment you are still deciding on.
Only the amount left after the reserve is genuinely investable capital. That is the number to use when you evaluate any deal.
Step 2: Plan estimated payments around the gain
The IRS says estimated payments are generally required when you expect to owe at least $1,000 after withholding and refundable credits, and your withholding and credits will fall below the smaller of 90% of the current-year tax or 100% of the prior-year tax. That prior-year figure rises to 110% if your prior-year adjusted gross income exceeded $150,000 ($75,000 if married filing separately).

For a one-time windfall, the same IRS page explains that a taxpayer with a large capital gain may annualize income and make an estimated or increased payment for the quarter in which the gain is realized. The 2026 Form 1040-ES repeats the $1,000 threshold and the 90% current-year test, and sets the prior-year comparison at 100% of 2025 tax, subject to special rules for higher-income taxpayers, farmers and fishermen.
In practice, a high earner with a large gain has two levers:
- Safe-harbor payments based on the prior year’s tax, which can be simple to calculate but may mean overpaying relative to the real liability.
- Annualized payments based on when the income actually arrived, which require more bookkeeping but match cash outflow to the event.
Your CPA should choose between them after seeing the full-year projection.
Step 3: Understand where oil and gas fits
Once the reserve is funded, some investors look at oil and gas because the tax code treats drilling costs differently from most other investments. The IRS oil and gas examination guide, Publication 5652, describes the pieces. An eligible U.S. oil and gas investment may generate IDC deductions under the §263© election, plus depreciation for tangible equipment and depletion as production occurs. The IRS is also clear that the actual result depends on the legal structure, the taxpayer’s role, the costs incurred and the limitation rules.
That last sentence is the most important one in this article. The deduction is a feature of how a specific project is built and how you hold it. It is not a feature of the words “oil and gas.”
Intangible drilling costs
IDC generally covers qualifying drilling and preparation costs with no salvage value: labor, fuel, site preparation, chemicals and similar items. Section 263© authorizes regulations that let taxpayers deduct qualifying IDC for U.S. wells, with special rules for wells outside the United States. According to Publication 5652, IDC may be expensed under §263© or amortized over 60 months under §59(e). For a liquidity-event investor, the first-year expensing is the reason the topic comes up at all, because it can offset other income in the year of the gain.
We cover the mechanics in more detail in our guide to intangible drilling costs for investors.
Tangible equipment
Equipment such as wellhead hardware and tanks is capitalized and recovered through depreciation rather than expensed at once. This is the slower part of the deduction stream, but it keeps working after the first year. See our breakdown of how tangible drilling costs are depreciated and the wider oil and gas depreciation methods.
Depletion
Depletion recovers your basis in the mineral property as the resource is produced. Independent producers and royalty owners may qualify for percentage depletion. Section 613A sets a 15% statutory rate for qualifying domestic oil and gas production and limits the deduction to 65% of adjusted taxable income, with disallowed amounts carrying to the following year. Treasury Regulation 1.613A-4 states the same limit and carryforward. Our write-up on percentage depletion rules shows why preparers run both the cost and percentage methods, and the royalty tax guide covers the 15% rate for mineral owners.
A side-by-side view of the three deduction types
| Cost type | What it covers | Typical tax treatment | Timing |
|---|---|---|---|
| Intangible drilling costs | Labor, fuel, site work, other non-salvage drilling costs | Expensed under §263© or amortized over 60 months under §59(e) | Largely in the year costs are paid or incurred |
| Tangible equipment | Physical, salvageable well equipment | Capitalized and depreciated | Over the recovery period |
| Depletion | Recovery of mineral-property basis | Cost or percentage depletion, subject to limits | As production occurs |
The classification of each cost is factual. Publication 5652 says costs must be analyzed individually and nonqualifying portions capitalized, which is why operator records and invoices matter.
What limits the deduction
The headline deduction is not the same as the deduction you can use this year. Four sets of rules sit between them.
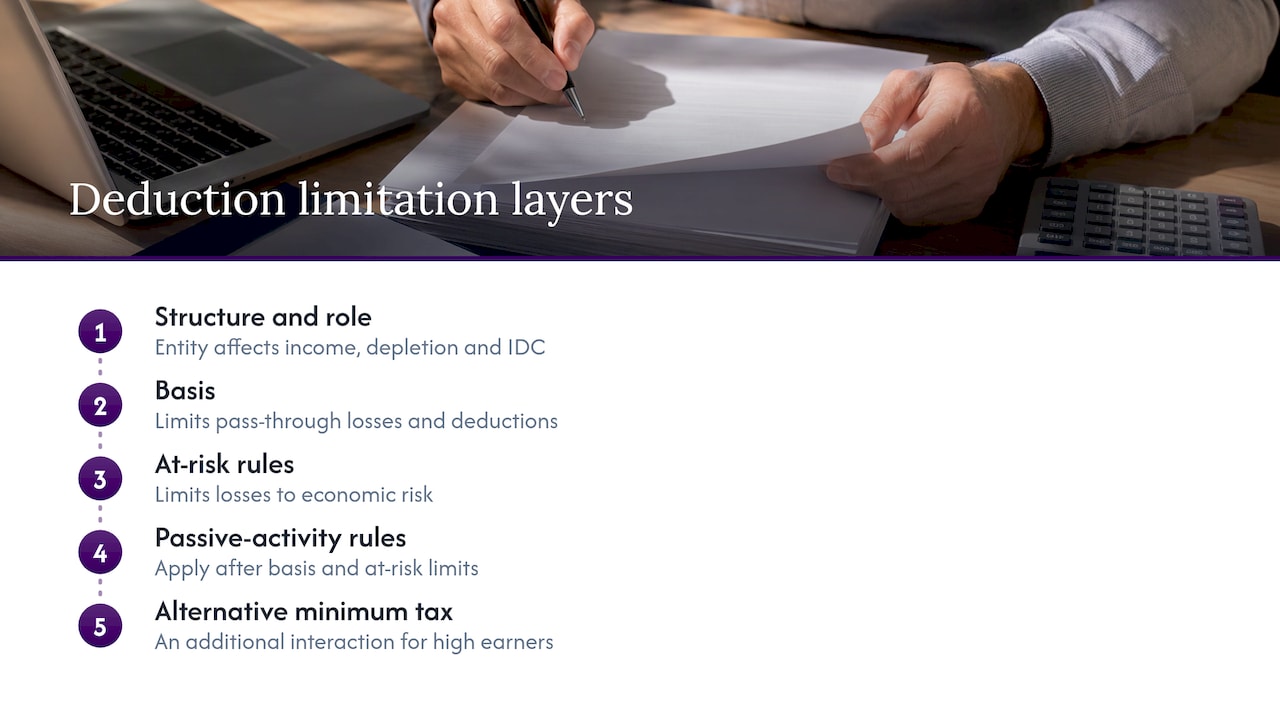
Structure and role. How you hold the interest changes everything. Income, depletion and IDC flow differently through partnerships, S corporations and C corporations, and some structures can create filing obligations in several states or investor-specific blockers. An industry journal piece on ownership forms for upstream investors walks through those trade-offs.
Basis. For pass-through entities, losses and deductions are generally limited to your basis, with unused amounts carried forward, according to the IRS Schedule K-1 instructions for S corporations.
At-risk rules. The same instructions note that at-risk rules can further limit losses to the amount for which you are economically at risk. Our article on nonrecourse debt and oil investors explains what counts.
Passive-activity rules. Those instructions also say passive-activity limits apply after basis and at-risk limits. Whether your interest is treated as passive depends on how it is held and how you participate, so it is a question for your CPA with the actual documents in hand.
One more item for high earners: the interaction with the alternative minimum tax. We address it in IDCs and the AMT.
Before you claim anything: a documentation checklist
Publication 5652 and related IRS materials make clear that classification and eligibility are matters of fact that must be documented. Before your return is prepared, confirm:
- The investment structure and how it reports to you (K-1 or otherwise).
- Your role in the activity.
- U.S. property location. The IDC rules differ for wells outside the United States.
- Cost classification. Each cost is IDC or a tangible capital expenditure, with invoices or operator statements to support it.
- Timing. The costs were paid or incurred in the tax year you want to deduct them.
- The election. An IRS private-letter ruling states that the §263© election is made by claiming IDC on the return for the first year the costs are paid or incurred. For §59(e), the S-corporation instructions say the shareholder, not the corporation, makes the election.
- Basis and allocation shown on the K-1.
Ask the operator in advance what reporting package you will receive and when. A deduction you cannot support is not a deduction.
Think about the exit on day one
First-year deductions are a timing benefit, and the tax code balances them on the back end. Under §1254, a disposition can treat the lesser of specified previously deducted oil and gas expenditures and depletion amounts, or the gain above adjusted basis, as ordinary income. In plain terms, deductions you took earlier can be recaptured as ordinary income when you sell.
That is not a reason to avoid the asset class. It is a reason to match the holding to your plan: some investors hold for the income stream for many years, and others model a sale. Our notes on oil and gas exit strategy lay out how to think about it. State taxes on production and on gains are another variable, so model them with your advisor.
A worked way to frame the decision
Here is a simple, hypothetical framing, not a projection and not a promise of any result.
Suppose you sold a business and have realized a large gain this year. After you fund the tax reserve, you have a pool of investable capital. For each possible use of that capital, ask:
- What does this do to this year’s taxable income, and is that benefit usable given the limits above?
- What does it do to future income and cash flow?
- What is the exit tax profile?
- How liquid is it, and how long am I comfortable holding?
- How does it diversify the rest of my balance sheet, which may be concentrated in one company’s equity?
If you want to see how the deduction math might look for your own numbers, our free oil and gas tax deduction calculator gives an estimate to bring to your CPA, and the wealth projection tool shows after-tax compounding. Doctors and other W2 professionals weighing the same question can read why doctors invest in oil and gas for tax savings.
Our perspective
Most people who come to us after a liquidity event are not short of opportunity. They are short of time and clarity. The tax bill is due, the reserve has to be set, and every advisor has a different idea of what to do with the rest.
We believe real assets deserve a place in that conversation. Direct ownership in U.S. energy projects carries a distinct tax profile, with IDC, depreciation and depletion, and it can pair large first-year deductions with long-term income. That is why we built Fieldvest around accredited investors who want that exposure without sourcing deals themselves.
Our approach is to do the screening first. We vet operators, present key project materials in a consistent format so deals can be compared side by side, and give you access to off-market opportunities designed for accredited investors. We want you and your CPA to see structure, costs and operator records before you commit a dollar.
Our advice is simple. Reserve your taxes, build the full-year projection, and then look at how much of the remaining capital should work in assets that carry their own deductions and income. Do it with your tax professional in the room.
Sharif
Where Fieldvest fits
Fieldvest is a marketplace where accredited investors can review vetted U.S. energy projects across three categories: producing assets, development projects and energy infrastructure. If you have a liquidity event behind you and want to see what is available, you can browse the options and compare project materials on the Fieldvest platform.
Bring the project documents to your CPA, run the numbers against your projected income, and decide with the full picture.
FAQ
Do I need to make estimated tax payments after selling a company?
Often, yes. The IRS generally requires estimated payments when you expect to owe at least $1,000 after withholding and credits and fall below the safe-harbor tests. If you have a large gain, you may be able to annualize income and pay for the quarter in which it was realized. Your CPA can calculate which method fits.
Can oil and gas deductions offset the gain from my sale?
They may reduce taxable income in the year they are claimed, but only to the extent the limitation rules allow. Basis, at-risk and passive-activity rules apply, and the result depends on how the investment is structured and your role in it. Have your CPA test your specific facts before you invest.
What is the difference between IDC and depletion?
IDC covers qualifying drilling and preparation costs and can generally be expensed under §263© or amortized over 60 months under §59(e). Depletion recovers your basis in the mineral property as production occurs, and some producers and royalty owners may use percentage depletion at 15%, subject to a 65% taxable-income limit.
Are the deductions permanent?
Not necessarily. Under §1254, a sale can treat previously deducted amounts as ordinary income, up to the lesser of those deductions or the gain above adjusted basis. Plan the holding period and the exit with your advisor from the start.
When should I talk to a tax advisor?
Before you sign anything, and ideally before the liquidity event closes. Planning on ownership, entity structure and charitable intent has the most room when it starts early, but there is still useful work to do after proceeds arrive.
Sources
- Large gains, lump sum distributions, etc. | Internal Revenue Service
- 2026 Form 1040-ES
- Publication 5652 (rev. 2-2023)
- 26 U.S. Code § 263 - Capital expenditures
- 26 U.S. Code § 613A - Limitations on percentage depletion
- 26 CFR § 1.613A-4
- 26 U.S. Code § 1254 - Gain from disposition of interest in oil, gas, geothermal, or other mineral properties
- IRS Instruction 1120 S Schedule K-1 (Rev. 2002)
- IRS private-letter ruling on the §263© election
- Ready for takeoff: How to prepare your company for a liquidity event
- Don’t blow the dismount! Wealth managers talk tax planning | InvestmentNews
- A Tax and Cash Checklist for an Equity Liquidity Event
- Income Tax Considerations in the Form of Ownership for Upstream Oil and Gas Investors | ABF Journal
Recommended

Get the Fieldvest Energy Brief
and AI-driven demand shifts — curated for accredited investors. Smart. Strategic. Tax-advantaged.