


The Waha basis is the gap between the price of natural gas at the Waha Hub in West Texas and the Henry Hub benchmark, calculated as Waha minus Henry Hub. Energy Information Administration](https://www.eia.gov/todayinenergy/detail.php?id=63044), said pipeline takeaway capacity struggled to keep pace with production.
TL;DR:
- Waha prices have traded below zero on nearly half of all trading days in 2024, with lows reaching negative $6.41 per MMBtu, due to pipeline bottlenecks.
- The difference between Waha and Henry Hub is now a recurring risk, driven by slow pipeline buildout, outages, and regional demand fluctuations, rather than one-off events.
- Pipeline capacity additions, such as Blackcomb and Hugh Brinson, are helping ease the oversupply but often lag behind production growth, prolonging negative pricing periods.
- The forward curve often underestimates Waha’s recovery potential until new capacity actually comes online, causing sudden cash-price shifts in response to operational updates.
- Producers keep pumping gas despite negative prices because oil revenue from associated wells offsets the transportation costs, while regional demand and storage constraints can deepen basis volatility.
Table of Contents
- Quick market snapshot: spot prices, extremes, and the trend
- Definition and contract mechanics: formula, settlement, and quoting
- Historical behavior and recent trends in negative pricing
- Primary drivers: capacity, production, outages, and demand
- Forward curve vs physical prices: where they diverge and why
- Where and how to monitor Waha basis day to day
- How Waha stacks up against other regional gas hubs
- Storage and inventories: a secondary lever on Waha prices
- Regulatory and policy factors shaping pipeline capacity
- What negative basis means for producers and consumers
- What this means for Permian-focused traders and analysts
- Sources
- FAQ
Quick market snapshot: spot prices, extremes, and the trend
Permian gas producers have spent the past two years selling into a bottleneck. Takeaway pipelines out of the basin have not kept up with associated gas volumes coming off oil wells, and the result shows up directly in the price at Waha.
- Frequency: Waha traded below zero on 46% of trading days in 2024, per EIA.
- Extreme low: the hub hit a low of negative $6.41 per MMBtu on August 29, 2024, based on NGI data cited by the EIA.
- Recent pace: reporting from NaturalGasIntel has tracked stretches where Waha spot prices went negative on 46 of 59 flow days, suggesting the pattern has persisted into subsequent periods rather than fading.
Negative pricing at Waha has been a near-annual feature of the hub since 2024, and the question for desks isn’t whether it recurs, but how deep and how often. (EIA)
Definition and contract mechanics: formula, settlement, and quoting
Waha basis is a straightforward differential, but the contract mechanics around it matter for anyone actually trading the exposure.
The formula is simple: Waha basis = Waha index price minus Henry Hub price. The ICE Waha Basis Future uses the Inside FERC index for the Waha side (Reference Price A) and NYMEX Henry Hub for the other leg (Reference Price B), according to ICE’s product documentation.
- Contract size: 2,500 MMBtu per lot, cash-settled rather than physically delivered.
- Quoting convention: prices quote to one hundredth of a cent per MMBtu ($0.0001), with up to 120 consecutive monthly contract periods listed, per the ICE product page.
- Settlement timing: cash settlement occurs against the published index values for the contract month, which means P&L on basis positions is locked in only after both reference prices are finalized, not on the trade date.
For desks running basis books, that settlement lag matters: a position that looks profitable intraday can shift once the final Inside FERC and NYMEX prints are in.
Historical behavior and recent trends in negative pricing
Negative Waha pricing is not a one-off event. It has become a recurring feature tied directly to how fast pipeline capacity gets built relative to production growth.
- 2024 baseline: Waha spot prices fell below zero on 46% of trading days, with the worst print at negative $6.41 per MMBtu on August 29, per EIA.
- Subsequent periods: NaturalGasIntel has documented stretches where the hub went negative on 46 of 59 flow days, indicating the frequency has not meaningfully eased on a sustained basis.
- Capacity correlation: episodes of deepest negative pricing have tracked periods when production outpaced available takeaway, with relief arriving only as new pipeline segments entered service.
The pattern desks should take from this: negative Waha days cluster around specific capacity and outage windows rather than spreading evenly across the calendar. Risk models built on an annual average will understate the tail risk on high-production, low-capacity days.
Primary drivers: capacity, production, outages, and demand
Waha goes negative when there is more gas at the hub than pipelines can carry out, forcing producers to pay to have it taken away rather than collect a positive price. Associated gas from Permian oil wells is largely a byproduct, so producers often keep pumping even when gas prices turn negative, because the oil revenue still justifies production.
- Takeaway capacity is the core constraint: when it lags production growth, Waha weakens, per EIA.
- Blackcomb and Hugh Brinson are among the newer pipeline projects adding egress capacity out of the Permian, with Blackcomb alone contributing roughly 2.5 billion cubic feet per day, according to EIA reporting.
- Matterhorn entered service as a capacity-relief project that EIA specifically flagged as easing prior bottlenecks.
- Double E, Solitude, and GCX round out the set of projects that have shifted the supply and demand balance at Waha as they reached in-service dates.
- Outages and weather compound the picture: unplanned pipeline outages concentrate gas at the hub with nowhere to go, while mild weather periods have driven regional gas prices negative in Texas and California by cutting demand, as Reuters reported in April 2026.
- Demand-side offsets, including LNG export growth and power burn, can absorb some of the oversupply but have not been enough on their own to eliminate negative pricing days.
Pro Tip: Track pipeline in-service dates alongside rig count and completions data, since a production ramp into a capacity-constrained window is the clearest early signal of a coming negative-price stretch.
Forward curve vs physical prices: where they diverge and why
The Waha forward curve and the physical cash price frequently tell different stories, and the gap between them is where a lot of basis trading risk lives.
Forwards price in expectations: analysts and traders build in anticipated pipeline in-service dates, so a curve can show tightening basis months before any new capacity actually flows gas. Physical prices, by contrast, reflect the market as it exists today, including any outage or weather shock.
- Liquidity differences mean forward months, especially those further out, can lag real-world developments simply because fewer trades are setting the price.
- Post-FID reactions have shown up repeatedly: NaturalGasIntel has reported cases where the forward curve underestimated Waha’s recovery until pipeline flows and final investment decisions actually materialized.
- In-service shocks can move cash prices fast. Projects like GCX, Blackcomb, Hugh Brinson, and Solitude have each produced near-immediate cash-price responses at Waha, in some cases flipping the hub from negative to positive within days, per NaturalGasIntel.
- Hedging approach: desks managing basis exposure often combine swaps with physical positions, or layer calendar spreads around known in-service windows, rather than relying on a single forward print.
The practical takeaway is to treat the forward curve as a working hypothesis, not a settled forecast, until pipeline flow data confirms the capacity is actually there.
Where and how to monitor Waha basis day to day
A basis desk needs a short list of sources it checks daily, not a dozen scattered feeds.
- Inside FERC publishes the Waha index used as the cash reference for settlement, making it the authoritative source for the physical price itself.
- NYMEX Henry Hub futures provide the other half of the basis calculation and the industry-standard U.S. benchmark.
- ICE’s Waha Basis Future product page carries live and historical futures pricing, contract specs, and open interest for the traded instrument.
- NaturalGasIntel (NGI) offers daily bidweek publications and reporting that connect price moves to specific pipeline and operational events.
- EIA’s Today in Energy series provides periodic, sourced analysis tying Permian capacity changes to Waha price behavior.
For real-time signals, watch ICE forward quotes and pipeline flow notices; for settlement and official index values, use Inside FERC; for longer historical study, pull archived time series from sources like Barchart. A standing checklist should include a daily forward-curve snapshot, a scan for pipeline force majeure or capacity restriction notices, and a review of the latest bidweek print.
How Waha stacks up against other regional gas hubs
Henry Hub is the national benchmark, but it is not the only point of comparison that matters for Permian gas. Regional hubs each reflect their own local balance of production, pipeline access, and demand, and Waha’s negative-pricing episodes stand out partly because of how extreme they get relative to peers.
Hubs tied to areas with ample pipeline takeaway and closer proximity to demand centers, such as the Gulf Coast corridor feeding LNG export terminals, rarely see the kind of deep negative prints that Waha has recorded. Their basis to Henry Hub tends to stay in a narrower band because supply and demand are better matched to available infrastructure. Appalachian hubs, which have faced their own historical takeaway constraints, offer a partial parallel: periods of pipeline buildout there also produced basis volatility, though the associated-gas dynamic in the Permian, where gas is a byproduct of oil drilling rather than the primary target, makes Waha’s swings more pronounced. Producers in the Permian keep pumping gas even at negative prices because oil revenue carries the economics, a dynamic that does not apply the same way in gas-focused basins.
The comparison matters for traders building cross-basin spread positions: Waha’s volatility is structurally different from, not just larger than, what shows up at better-connected hubs, and models that treat all basis risk as interchangeable will misprice the tail.
Storage and inventories: a secondary lever on Waha prices
Storage plays a smaller role at Waha than at hubs with easier pipeline access, mainly because the basin’s storage infrastructure is limited relative to the volume of gas being produced. When takeaway pipelines are full and storage nearby is also constrained, producers and gatherers have few options left besides accepting a negative price or curtailing output.
Regional storage inventories still matter at the margins. Elevated storage levels heading into shoulder seasons, when heating and cooling demand are both low, can compound the pressure that already builds from oversupply at the hub. The Reuters report on negative Texas and California gas prices in April 2026 pointed to mild weather cutting demand as a contributing factor, and thin storage buffers in such windows leave producers with fewer places to park unsold gas.
For analysts modeling Waha risk, storage data is worth tracking as a secondary signal rather than a primary driver. Pipeline capacity additions and production growth explain most of the variance in Waha pricing, but a storage-constrained shoulder season can turn an already weak basis into an outright crisis for a few trading days.
Regulatory and policy factors shaping pipeline capacity
Pipeline capacity does not appear overnight, and the regulatory path a project takes directly affects how quickly Waha basis can tighten. Interstate pipelines typically require federal certification, and the timeline for permitting, environmental review, and construction can stretch a project’s in-service date by months or years relative to its original announcement.
That lag is part of why forward curves sometimes misjudge Waha’s trajectory: a pipeline that clears its final investment decision still has to clear regulatory review and construction before it adds a single cubic foot of capacity. Delays at any stage, whether from permitting challenges, right-of-way disputes, or construction setbacks, push out the relief date and extend the window of negative pricing.
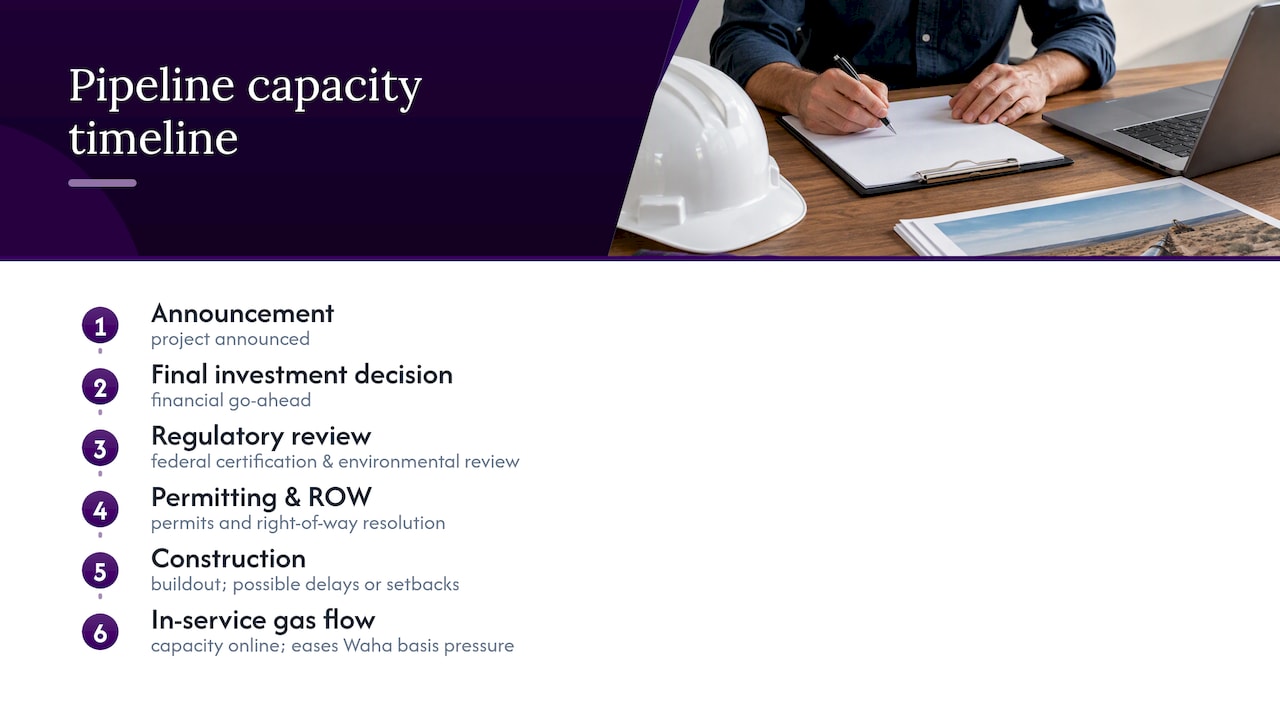
Policy shifts at the federal level that affect permitting timelines for interstate gas infrastructure carry real weight for Waha specifically, because the basin’s gas problem is fundamentally an infrastructure problem. Projects like Blackcomb and Hugh Brinson only ease basis pressure once they are actually flowing gas, and every regulatory step between announcement and in-service date is a variable that traders and analysts need to track alongside the engineering timeline.
What negative basis means for producers and consumers
Negative Waha pricing is not an abstract market quirk. It has direct economic consequences for the people producing and consuming Permian gas.
Producers selling associated gas at a negative price are effectively paying to have it removed, a cost that gets absorbed because the oil revenue from the same wells still clears. That math works for integrated operators but squeezes smaller producers with thinner margins, and it has pushed some operators toward flaring or shutting in gas production during the worst pricing stretches rather than paying to move it.
On the consumer side, the picture is more mixed. Gas-fired power plants and industrial users located near the Permian can benefit from unusually low input costs during negative-price periods, which has made West Texas an attractive location for new power generation and industrial demand. Further downstream, the pricing volatility at Waha has limited direct effect on retail consumers elsewhere, since Henry Hub remains the dominant national benchmark for most delivered gas.
For investors with exposure to Permian-focused energy projects, the basis dynamic is a reminder that wellhead economics depend on more than the headline price of oil. Gas realizations, and the pipeline capacity that determines them, are part of the return calculation. Readers evaluating that kind of exposure can find more context on how U.S. energy demand growth is shaping investor interest in why high-earning Americans are turning to oil and gas.

What this means for Permian-focused traders and analysts
Waha basis should stay volatile through the next few years, even with Blackcomb, Hugh Brinson, and other projects adding capacity, because production growth tends to fill new pipelines faster than the market expects. The three signals worth watching closely: pipeline in-service dates slipping against announced schedules, production growth outpacing the capacity being added, and shoulder-season demand drops that compound storage limits. Investors evaluating Permian-linked energy projects should treat gas basis as a line item in due diligence, not an afterthought, since it directly affects wellhead cash flow regardless of how oil prices behave.
— Sharif
Sources
- Natural gas pipeline capacity from the Permian Basin is set to increase — U.S. EIA
- Is Waha natural gas on pace to shatter annual record for negative prices? — NaturalGasIntel
FAQ
What is the Waha basis?
The Waha basis is the price difference between natural gas at the Waha Hub in West Texas and the Henry Hub benchmark, calculated as Waha minus Henry Hub. A negative value means Permian gas is trading below Henry Hub, which happened on 46% of trading days in 2024 according to EIA.
Where does America get most of its natural gas?
U.S. natural gas production comes primarily from a handful of shale basins, with the Permian Basin in West Texas and southeastern New Mexico serving as one of the largest sources, alongside Appalachian shale formations. Permian gas is often produced as a byproduct of oil drilling rather than as the primary target.
What are the latest news on natural gas prices today?
Natural gas prices move daily based on weather, storage levels, and regional pipeline conditions, with outlets like NaturalGasIntel publishing ongoing coverage of hub-specific moves. Regional hubs like Waha have continued to see frequent negative pricing tied to pipeline capacity constraints.
What is the major natural gas trading hub in the US?
Henry Hub, located in Louisiana, serves as the primary U.S. natural gas pricing benchmark and the settlement point for NYMEX natural gas futures. Regional hubs like Waha trade at a basis, or differential, relative to Henry Hub rather than as independent benchmarks.
How does the Waha basis affect energy investors?
A negative Waha basis reduces the cash realized from gas production in the Permian, which can affect the economics of gas-weighted projects even when oil prices stay strong. Investors researching tax-advantaged energy opportunities can review project-specific economics using tools like Fieldvest’s oil and gas tax deduction calculator.
Recommended

Get the Fieldvest Energy Brief
and AI-driven demand shifts — curated for accredited investors. Smart. Strategic. Tax-advantaged.



